
If your house was built before 1978, federal law requires you to disclose any known lead paint to every buyer, give them an EPA pamphlet, and allow a 10-day window for an inspection. That is the floor. What most listing guides skip is what comes next: FHA and VA appraisers can turn visible lead paint into a required repair, which freezes the deal until it is fixed at your expense. A cash buyer makes no appraisal. That difference matters when the repair bill is steep.
What the Federal Disclosure Law Actually Requires
The Residential Lead-Based Paint Hazard Reduction Act (42 U.S.C. §4852d) applies to any sale of residential property built before 1978. It is a federal law. It applies in all 50 states and does not depend on whether lead was ever confirmed in the home. The pre-1978 construction date is the only trigger.
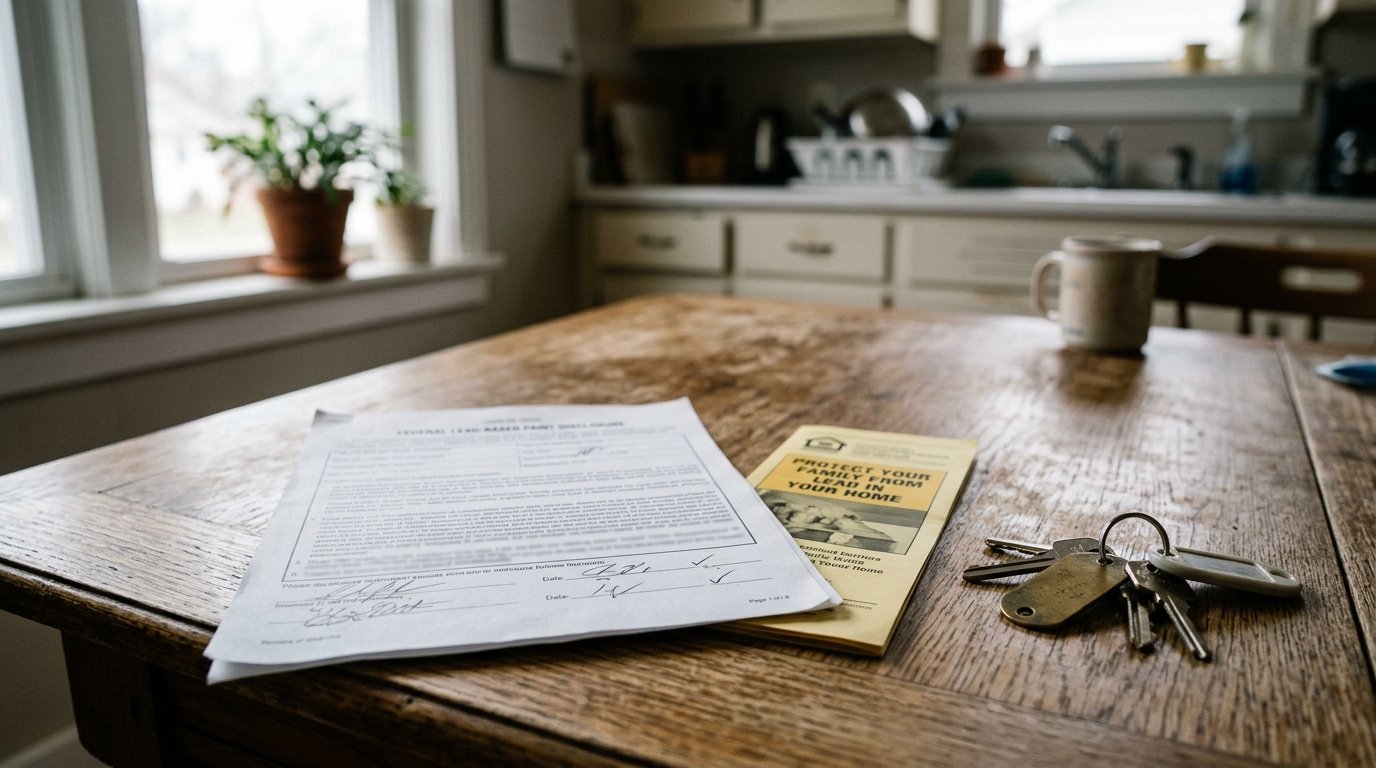
Before the contract is signed, three things must be delivered to the buyer:
- The EPA-approved disclosure form stating what you know, or do not know, about lead paint and lead hazards in the home
- Any records or inspection reports about lead paint that you already have in your possession
- A copy of the EPA pamphlet "Protect Your Family From Lead in Your Home"
By default the buyer then has 10 days to conduct a risk assessment or inspection. Both parties can agree to a shorter period, or the buyer can waive the right in writing. What you cannot do is skip the disclosure form entirely.
"Not knowing" is not a liability, but guessing is. If you have a lead paint report from a prior buyer's inspection, you must share it. If you have no records and no knowledge of any hazard, you disclose exactly that. The law requires disclosure of known conditions, not omniscience.
The penalty for a violation is real. HUD and the EPA can fine sellers and their agents up to $16,000 per violation, and willful non-disclosure has resulted in civil liability in multiple states. The disclosure form is not paperwork to skip.
Why FHA and VA Appraisers Turn Lead Paint Into a Required Repair
This is where the disclosure ends and the actual transaction problem begins.
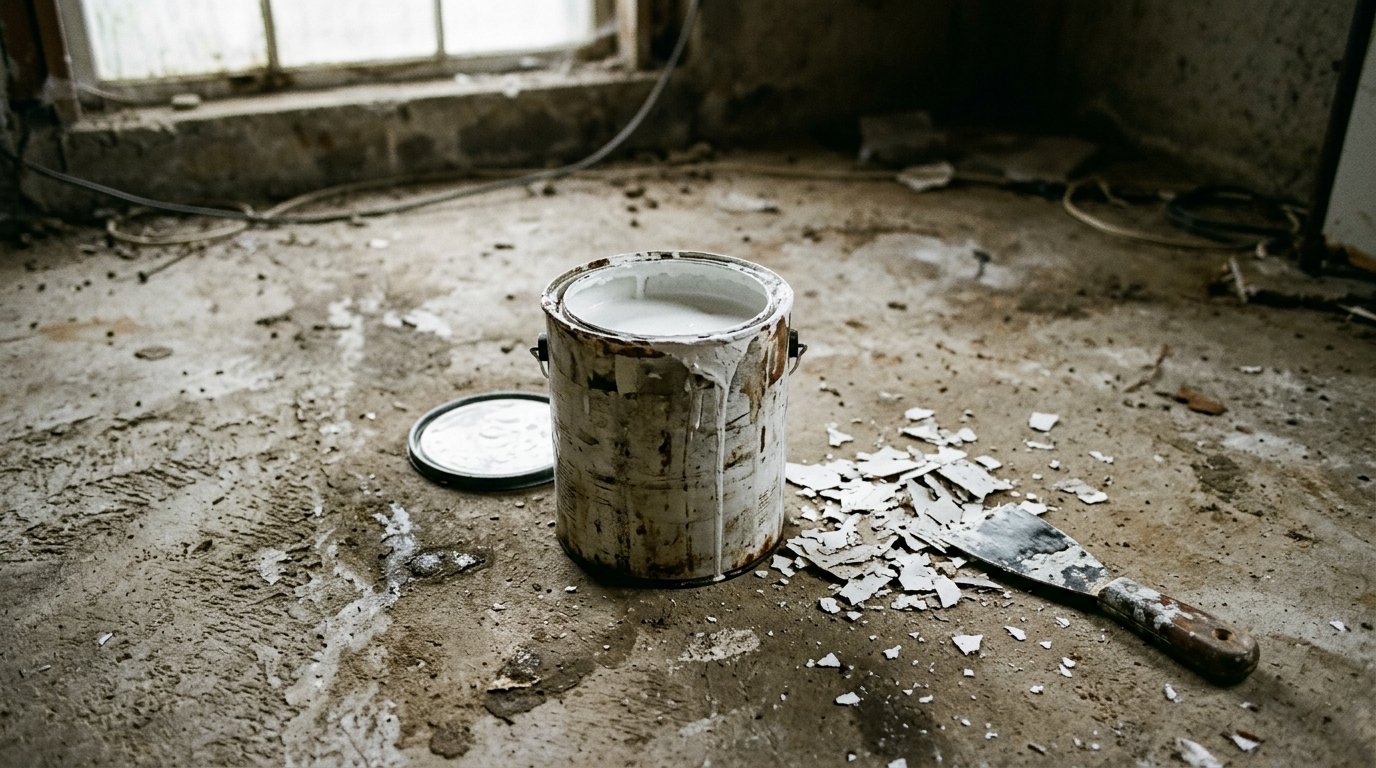
FHA loans are governed by HUD Handbook 4000.1. Section II.A.8 requires the FHA appraiser to flag deteriorated paint conditions in pre-1978 homes. "Deteriorated" means chipping, peeling, or flaking, whether on interior window sills, exterior trim, garage walls, or any other painted surface that is not fully intact. When the appraiser flags it, the condition becomes a required repair. The loan will not close until an EPA-certified contractor corrects the problem and the appraiser returns for a re-inspection.
The VA applies the same standard. Chapter 12 of the VA Lender's Handbook (Pamphlet 26-7) classifies deteriorated paint in pre-1978 homes as a minimum property requirement violation. The outcome is identical: required repair, no exceptions for as-is closings.
Conventional buyers with Fannie Mae or Freddie Mac financing operate under softer rules. Those guidelines ask appraisers to report health and safety deficiencies but do not create the same hard stop. A conventional appraiser may or may not flag peeling paint as a required condition. The catch is that many lenders layer their own overlays that push toward the FHA standard, and a buyer who switches lenders mid-contract can reopen the repair question entirely.
The practical effect: a pre-1978 house with any visibly deteriorated paint has a reduced buyer pool. Roughly 30 percent of purchase mortgages in recent years have been FHA or VA. Those buyers are blocked until the paint is corrected.
What Remediation Actually Costs
The EPA's Renovation, Repair, and Painting Rule (40 CFR Part 745, effective April 2010) requires that contractors disturbing lead-painted surfaces in pre-1978 homes be certified as EPA Lead-Safe Renovators. The threshold is 6 square feet of disturbed surface indoors per room, or 20 square feet outdoors. Scraping, sanding, cutting, or demolishing painted surfaces above those limits triggers the certification requirement. You cannot hire an uncertified handyman and call the repair complete. An FHA or VA appraiser will ask for documentation before signing off.
What remediation costs in practice (2026 ranges, EPA-certified contractors):
- XRF testing to confirm lead presence and location: $300 to $700
- Encapsulation of one or two rooms with intact but aging paint: $1,500 to $3,500
- Abatement of exterior trim on a medium-size home: $4,500 to $8,000
- Full abatement of interior and exterior on a 1,500 square foot pre-1978 home: $10,000 to $18,000
Encapsulation covers the painted surface with a bonded sealant rather than removing the paint. It is cheaper and often acceptable for intact paint that is not actively deteriorating. But if the appraiser flags chipping or flaking, most FHA and VA reviewers require abatement, not encapsulation. There is no point paying for encapsulation and having the appraiser reject it.
A Worked Example: 1964 Colonial in Baltimore County, Maryland
A concrete scenario puts the math into focus.
The house is a 1964 colonial in Baltimore County, Maryland, listed at $275,000. Two weeks after listing, a buyer with FHA financing signs a contract at $271,000. The FHA appraiser visits. The exterior trim has peeling paint on three sides of the house. One interior window sill in the primary bedroom has visible chipping. The appraiser notes both conditions as required repairs.
The seller gets one quote from an EPA-certified contractor: $7,800 to abate the exterior trim and encapsulate the interior window sill.
Option A: Fix it and close the FHA deal. Cost breakdown: $7,800 in repairs, $350 appraiser re-inspection fee, 5.5 percent real estate commission ($14,905), $5,500 in seller closing costs. Net proceeds: approximately $242,445. Timeline from the appraiser's flag to close: four to six weeks, assuming the contractor is available and no additional lead is found once work begins.
Option B: Accept a cash offer, sell as-is. The cash offer reflects the repair cost and the buyer's margin for uncertainty. An offer in the $235,000 to $245,000 range is realistic for this condition. At $240,000 cash with no commission charged and no closing costs passed to the seller, net proceeds: $240,000. Timeline: seven days from signed contract.
In this example, Option A nets about $2,400 more than Option B. It also requires a contractor, a re-inspection, and three to five extra weeks. More importantly, it carries a hidden risk: if the contractor uncovers additional deteriorated surfaces not visible during the initial walkthrough, the repair scope expands and the appraisal process restarts. That is not a theoretical risk in older homes with multiple painted surfaces.
Change one variable and the math flips. If the appraiser flags the whole first floor rather than a single window sill, the abatement quote rises to $14,000. Option A net falls to $236,195. Option B at $240,000 wins outright, before accounting for the extra weeks of carrying costs.
Maryland is a useful state to name here. The state's lead poisoning prevention framework, codified at Health-General Article §§6-801 through 6-874, is one of the most developed in the country. Its strongest requirements apply to rental properties where children under 6 reside, but the regulatory infrastructure means Maryland has a deeper pool of EPA-certified abatement contractors than most states. That usually keeps quotes competitive. It also means appraisers and inspectors in this market are experienced at finding lead conditions that sellers in less-regulated states might not expect to be flagged. A Baltimore County home with multiple painted surfaces from the 1960s is more likely to generate a substantial required-repair list than a similar home in a state where the inspection culture is thinner.
If you own a pre-1978 home in Maryland and are weighing your options, we buy houses in Maryland directly, with no appraisal and no requirement that the lead paint be addressed before closing.
Who Should Not Take a Cash Sale
A cash offer below market is the right trade in specific situations. It is not always the right trade, and printing the honest case against it here is more useful than pretending otherwise.
A traditional listing is probably the better path if:
- The deteriorated paint is limited to one small area, and a single contractor quote comes in under $3,000. At that repair cost, an FHA deal still nets more than most cash offers after accounting for the difference.
- The house is otherwise in strong condition. A pre-1978 home with intact paint, updated mechanicals, and a good roof will attract conventional buyers who are not subject to the FHA appraisal stop. Accepting a cash discount on a move-in-ready house does not make financial sense.
- You have six months or more before you need to sell. Time absorbs most of the complexity. A unhurried remediation project, done by an EPA-certified contractor on a reasonable schedule, adds the least carrying cost and the fewest surprises.
A cash sale tends to be the cleaner choice when:
- The lead paint is pervasive or on surfaces that are difficult and expensive to remediate, such as decorative millwork, staircase spindles, or complex exterior profiles where abatement is labor-intensive.
- The house has other condition issues alongside the paint. An FHA appraiser inspecting one thing will note everything. If the roof is also aging, the HVAC is old, or there is any visible moisture damage, the required-repair list can cascade well beyond the original paint estimate.
- The market is slow and days-on-market are climbing. Each additional month of carrying costs narrows the gap between the listing net and the cash net. At $1,500 to $2,000 per month in taxes, insurance, and utilities on a vacant pre-1978 home, a four-month delay closes a lot of that $2,400 gap from the example above.
A traditional listing usually nets more when the house is in good condition and the seller has time. Lead paint on a deteriorating surface, in a house where the paint is actively failing, is one of the situations where "good condition" is already off the table. If you are working through the general repair-cost math, the major repairs situation page covers the framework in more detail.
For a written offer with no obligation, call 208-540-8257 or visit the offer page. We buy in all 50 states and can usually give you a number within 24 hours of seeing the property details. Check with a local real estate attorney on any state-specific disclosure requirements that apply in your area before signing anything.
Common Questions
Do home sellers have to disclose lead paint?
Yes, if the home was built before 1978. Federal law (42 U.S.C. §4852d) requires sellers to complete a disclosure form, provide any existing lead paint records, and give buyers the EPA pamphlet "Protect Your Family From Lead in Your Home" before the contract is signed. This applies in every state. The 10-day inspection window is the buyer's default right, but they can waive it in writing.
What happens if you sell a house with lead paint and do not disclose it?
HUD and the EPA can assess civil fines up to $16,000 per violation for failures to disclose. Beyond the fine, a buyer who later discovers undisclosed lead paint has grounds for a civil lawsuit. The disclosure requirement is not a technicality, and "I didn't know the form was required" is not a defense once the pre-1978 date is established.
How expensive is it to remediate lead paint in a house?
It depends on the scope. Encapsulating a small area runs $1,500 to $3,500. Abating exterior trim on a medium home runs $4,500 to $8,000. Full interior and exterior abatement on a 1,500 square foot pre-1978 home can reach $10,000 to $18,000. All work must be performed by an EPA Lead-Safe Certified contractor under 40 CFR Part 745. An initial XRF test to map the extent of lead-containing paint costs $300 to $700 and is usually worth doing before accepting any quote.
Can you sell a pre-1978 house as-is without fixing the lead paint?
Yes, with two conditions. First, you must still provide the federal disclosure form and EPA pamphlet to every buyer, regardless of the sale terms. Second, a buyer using FHA or VA financing cannot close on the house if an appraiser flags deteriorated paint as a required repair, unless that repair is completed first. A cash buyer, or a conventional buyer whose lender does not impose the same appraisal stop, can purchase the home as-is without any remediation.